






-
09:00- 09:15 Welcome and introduction by Morten Hegna, Sjur Westgaard and Morten Risstad
-
09:15-10:00 Introduction to energy markets. Risk and return characteristics of energy futures and spot markets.
-
10:15-11:00 Risk measures: Volatility and Correlation, Value at Risk (VaR), Expected Shortfall (ES).
Empirical risk characteristics of electricity spot and futures markets. Risk characteristics in energy calendar spreads and energy cross commodity spreads.
-
11:15-12:00 How to model and predict electricity price distributions and risk using quantile regression with fundamental supply and demand factors.
How fundamentals like fuel prices, forecast of demand and supply, wind and solar influence the price risk.
-
12:00-13:15 Lunch
-
13:15-14:00 Modeling volatility and correlation in energy markets. Moving average models for volatility and correlation.
Uni- and multivariate GARCH models. Models based on intra-daily data. Models based on implied volatility.
-
15:15-16:00 Case studies recent trading losses in oil, natural gas and electricity futures and option markets
(China Aviation Oil, Amaranth, Bank of Montreal, Optionsellers.Com)
Energy Risk Modelling
This popular two-day in-depth workshop is dedicated for risk management professionals, analysts and traders wanting to gain insights into risk modelling of energy markets.
Learn how to measure and model risk in energy portfolios
More volatile energy markets, combined with complex trading and hedging portfolios have increased the need for measuring risk of individual contracts and whole portfolios, as well as at corporate level (Enterprise risk management). Furthermore, understanding the dynamics and determinants of volatility, correlation and risk (value at risk and expected shortfall) in energy markets is essential.
Registration is now open.
For questions, please contact:
Seminar agenda
Speakers
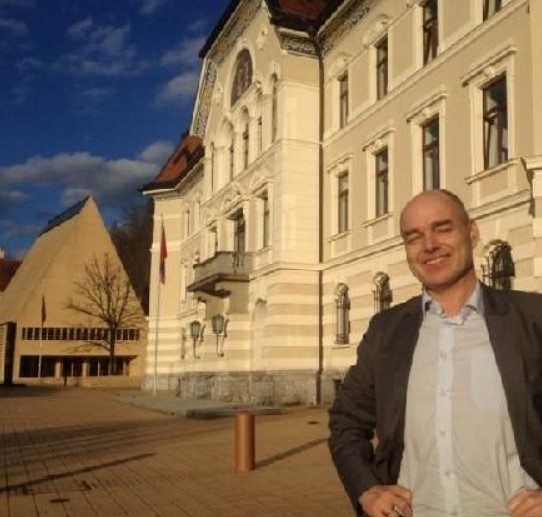
Sjur Westgaard
MSc and Phd of Industrial Economics from Norwegian University of Science and Technology and a MSc of Finance from Norwegian School of Business and Economics
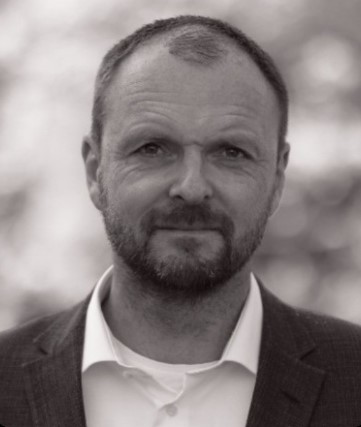
Morten Risstad
Associate Professor Department of Industrial Economics and Technology Management Norwegian University of Science and Technology
Informations

Webinar

February 4, 2025
-
February 5, 2025
09:00 - 16:15 CET
