

What is energy security? How geopolitical risk reshapes power and gas prices
Energy security is usually discussed as a policy objective. For anyone trading or buying energy, it is more useful to treat it as a price signal.
Markets price the probability of a supply disruption long before any disruption occurs, and often price it even when nothing happens at all. The risk premium embedded in a forward curve is the market’s assessment of how likely it is that molecules or electrons will fail to arrive - and that assessment shifts with news, not with physical events.
What energy security actually means
The term covers three distinct things that are frequently conflated.
- Availability is the physical question: can supply be delivered when it is needed? This covers import dependency, infrastructure resilience, storage levels and the diversity of supply routes.
- Affordability is the economic question. Supply that arrives at a price that damages industrial competitiveness or household budgets is not generally regarded as secure, even though the molecules turned up.
- Resilience is the systemic question: how well can the system absorb a shock and recover? A country with high import dependency but multiple routes, deep storage and flexible demand may be more resilient than one with lower dependency and a single supply corridor.
The relative weight given to each varies considerably by country. An import-dependent industrial economy places heavy emphasis on affordability. A country with abundant domestic hydro but weak interconnection worries about drought. A system built around a single pipeline corridor is dominated by route risk, regardless of price.
Time horizon matters as much as geography. Over days, energy security concerns system operation and reserve margins. Over months, it concerns storage trajectories and contract cover. Over years, it concerns infrastructure and import diversification, where policy operates but price signals are weakest.
How geopolitical events feed through to power and gas prices
The transmission chain passes through gas, and tracking each step is important because every stage either weakens or strengthens the signal.
A supply risk emerges - a sanctions decision, a shipping route disruption, an infrastructure failure. The first market to respond is LNG, because cargoes are physically diversible and traders immediately reassess where they will land. Freight rates and inter-basin spreads move first, particularly the relationship between TTF (Title Transfer Facility, the Dutch benchmark for European gas) and JKM (Japan Korea Marker, the Asian LNG benchmark).
That spread determines cargo direction. When TTF trades at a sufficient premium to JKM, cargoes head to Europe; when the relationship inverts, they head to Asia. Europe’s marginal supply is therefore set by global competition for flexible cargoes, which is why an Asian cold snap can lift European gas prices even without any European event.
TTF then transmits into power. Across most European systems, gas plants set the marginal price for a substantial share of hours, so the power curve inherits gas price movements scaled by plant efficiency and carbon cost. That mechanism is set out in What is the merit order, and how are power prices set?
The scaling varies: during hours of high renewable output, gas is not marginal and transmission is limited. In cold winter evenings, it approaches a one-to-one ratio. As renewable penetration increases, the average transmission capacity diminishes, but peak-hour transmission remains robust - resulting in broader price spreads rather than consistently higher prices.
Recent examples: shipping routes, supply disruptions, sanctions
Europe’s structural rebalancing away from Russian pipeline gas remains the dominant case study. The replacement of pipeline volumes with seaborne LNG converted Europe from a market supplied by fixed infrastructure into one competing globally for flexible cargoes, thereby raising both the average price level and its sensitivity to distant events.
That transition has now been formalised in law. The EU adopted a regulation phasing out Russian gas imports, with a stepwise prohibition running through 2026 and 2027 - LNG imports ending by the start of 2027 and pipeline gas by autumn 2027, alongside prior authorisation requirements and anti-circumvention provisions. Member states were required to submit national diversification plans. What had been a market-driven adjustment became a legal deadline, thereby changing how the residual risk is priced.
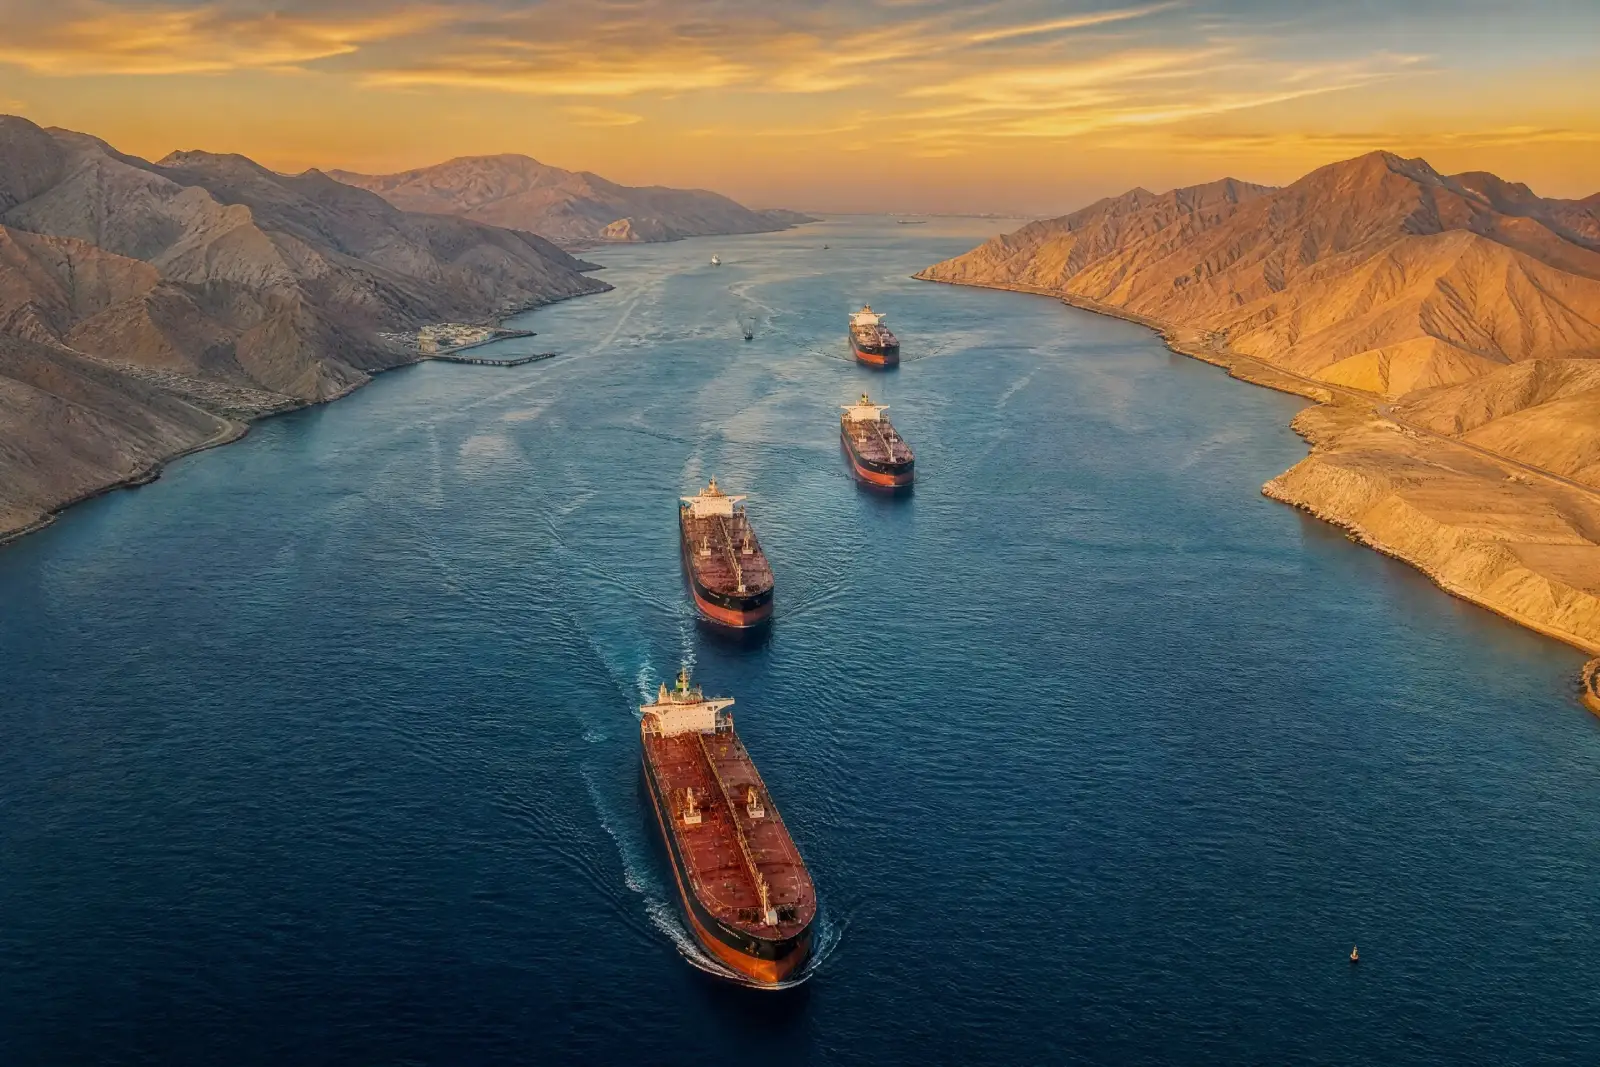
Shipping route disruptions offer a clearer illustration of premium dynamics. Attacks on vessels in the Red Sea pushed LNG carriers onto the Cape of Good Hope routing, adding roughly a week to voyages from the Gulf to Europe. No cargo was lost, but effective supply tightened because vessels spent longer at sea. The price response was real but moderate, and it decayed as the market absorbed the new routing.
The key lesson is that decay patterns are practically useful. Premia linked to events that decrease flexibility but do not eliminate volume tend to diminish within weeks, while premia associated with permanent supply removal tend to last. Recognising the difference between these two early in a news cycle is where most trading value resides.
Why energy security and the energy transition sometimes pull in different directions
The two goals are frequently presented as aligned. Domestic renewables displace imported fuel, so building them improves security while cutting emissions. That is true in the long run and misleading in the short run.
The tensions are specific:
- Timing, where security concerns are immediate and transition benefits accrue over decades, so a supply crisis produces pressure for firm capacity that is available now
- Firmness, since a system with high renewable penetration and insufficient flexibility can be more vulnerable to weather-driven scarcity, not less
- New dependencies, as critical minerals, battery cells and manufacturing capacity concentrate in a small number of countries
- Infrastructure lock-in, where LNG import terminals built for security reasons carry contractual commitments extending decades past the point demand is projected to fall.
Where the two align most clearly is flexibility. Storage, demand response, interconnection and firm low-carbon generation all improve resilience and support decarbonisation simultaneously. This is a significant part of the renewed interest in nuclear, including the modular designs discussed in What are small modular reactors? A beginner’s guide to SMRs
How traders and buyers price in geopolitical risk
Geopolitical risk is difficult to model because the events are rare, poorly correlated with historical patterns, and resolve in discrete jumps rather than continuously.
The most common approach is an explicit risk premium: pricing forward contracts above the level justified by fundamentals alone, with the gap representing the cost of insuring against disruption. Winter contracts typically carry the largest premium because the system has the least slack then.
Optionality often holds more value than directional bets. Geopolitical events cause sharp, asymmetric moves, allowing options-based strategies to profit from upside without needing to predict whether a specific event will happen. Physical optionality is embodied in storage capacity, flexible supply contracts, and interruptible demand, all serving the same purpose.
Hedging horizons tend to lengthen when perceived risk rises. Industrial buyers who normally hedge a season ahead may extend their horizons to multiple years, shifting liquidity along the curve and potentially moving forward prices.
Scenario analysis carries more weight here than in most areas of energy trading, precisely because historical distributions are a poor guide. Testing a portfolio against a defined disruption - a corridor closure, a major outage, or a sanctions escalation - yields more useful insight than a volatility estimate calibrated to a calm period.
The discipline that separates good practice from bad is distinguishing what is already priced from what is not. By the time a risk is widely discussed, it is generally in the curve. The positions that pay are those taken on transmission mechanisms others have not yet worked through.
Conclusion
Energy security is best understood as the market’s continuously updated assessment of whether supply will arrive, expressed as a premium over fundamental value. That premium moves with perception and can persist for months without any physical disruption.
Three key aspects to monitor include chokepoints, which pose the greatest risk due to the limited maritime corridors carrying most seaborne energy, and no contractual diversification can fully mitigate this physical concentration. Additionally, contract renewals are critical as Russia's phase-out deadlines near and replacement volumes are finalised. Lastly, storage levels before each winter are the most dependable indicator of the European system's buffer capacity.
The structural point is that Europe swapped infrastructure risk for market risk. Pipeline dependence meant a small number of large, visible vulnerabilities. LNG dependence means many smaller ones, spread across a global market where a cold winter in Asia is now a European price event.